Introduction
Understanding the difference between markup and margin is essential for running a profitable business. Whether you own a retail store, sell products online, manage an e-commerce brand, or provide professional services, these two financial metrics help you make better pricing decisions.
Although markup and margin are closely related, they measure profitability in different ways. Markup shows how much you add to a product’s cost to establish its selling price. Margin shows what percentage of the selling price remains after accounting for the relevant cost.
Confusing these metrics can lead to underpricing, unrealistic profit expectations, and inaccurate financial forecasts. For example, adding a 30% markup to a product does not produce a 30% profit margin.
In this guide, you’ll learn what markup means, how to calculate markup and margin, the difference between markup vs margin, and how to use both metrics when pricing products in the United States.
What Is Markup?
Markup is the amount added to the cost of a product or service to determine its selling price. Businesses commonly express markup as a percentage of the original cost.
Retailers, wholesalers, manufacturers, and online sellers use markup to establish prices that cover product costs and contribute to business profitability.
For example, suppose a US retailer purchases a product for $50 and applies a 40% markup.
- Original cost: $50
- Markup percentage: 40%
- Markup amount: $20
- Selling price: $70
The retailer adds $20 to the original cost, resulting in a selling price of $70.
However, the $20 difference is not necessarily the retailer’s final net profit. The business may still need to pay shipping, payment processing fees, advertising costs, rent, payroll, and other operating expenses.
Markup Formula
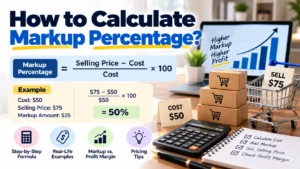
The standard markup percentage formula is:
Markup % = Selling Price – Cost \ Cost * 100
To calculate the selling price from a known markup percentage, use:
SellingPrice=Cost(1+MarkupRate)
Use the markup rate as a decimal in the second formula. For example, 40% becomes 0.40.
Example: If a product costs $80 and the business applies a 25% markup:
$80 * (1+0.25) = $100
The selling price is $100, and the markup amount is $20.
What Is Profit Margin?
Profit margin measures profit as a percentage of revenue. It helps businesses understand how much of their sales revenue remains after deducting a specified category of costs.
The term profit margin can refer to different measurements, including gross profit margin, operating profit margin, and net profit margin. These metrics differ according to which expenses are included.
For a basic pricing comparison, markup is typically compared with gross profit margin, using the same product cost and selling price.
For example, if a product costs $50 and sells for $70, the gross profit is $20. The gross profit margin is calculated using the selling price rather than the original cost.
Gross Margin % = Selling Price – Cost \ Selling Price * 100
= $70 – $50 \ $70 * 100 = 28.57%
The business earns a gross profit of $20, equivalent to a 28.57% gross margin on the sale before other expenses.
A positive gross margin does not automatically mean the business is profitable overall. Operating expenses, taxes, interest, and other costs can reduce or eliminate net profit.
Markup vs Margin: What Is the Difference?
The main difference between markup vs margin is the number used as the denominator when calculating the percentage.
- Markup measures profit relative to cost.
- Margin measures profit relative to selling price.
Both calculations can use the same dollar amount of gross profit, but they produce different percentages.
Markup vs Margin Comparison Table
| Feature | Markup | Gross margin |
| What it measures | Profit relative to cost | Profit relative to sales |
| Formula | Profit ÷ Cost × 100 | Profit ÷ Selling price × 100 |
| Main purpose | Setting prices | Evaluating gross profitability |
| Percentage for a $50 cost and $70 price | 40% | 28.57% |
| Denominator | Original cost | Selling price |
| Typical business use | Product pricing | Financial performance analysis |
For a profitable sale with a positive cost, markup is higher than gross margin because the cost is lower than the selling price. The dollar profit remains the same; only the reference amount changes.
Example: Comparing Markup and Margin on the Same Product
Imagine a small US e-commerce business buys a product for $60 and sells it for $100.
Product cost
$60
Selling price
$100
Gross profit
$40
Markup
66.67%
Gross margin
40%
The markup calculation is:
$100 – $60 \ $60 * 100 = 66.67%
The gross margin calculation is:
$100 – $60 \ $100 * 100 = 40%
The business earns $40 in gross profit per unit, but that represents a 66.67% markup and a 40% gross margin. These figures are not interchangeable.
How to Calculate Markup Percentage
Calculating markup percentage helps business owners determine how much they have added to the cost of a product.
Follow these steps:
- Determine the total cost used for pricing.
- Identify the intended selling price.
- Subtract the cost from the selling price.
- Divide the difference by the cost.
- Multiply by 100 to convert the result into a percentage.
Markup Calculation Example
Suppose a retailer purchases a product for $120 and sells it for $180.
| Calculation | Amount |
| Selling price | $180 |
| Product cost | $120 |
| Gross profit | $60 |
| Gross profit ÷ product cost | $60 ÷ $120 |
| Markup percentage | 50% |
The retailer applies a 50% markup to the product’s cost.
If you want to calculate markup quickly for different prices, a markup percentage calculator can help simplify the arithmetic. Check that the calculator supports the specific calculation you need before relying on its results.
How to Calculate Profit Margin
Profit margin uses revenue as the denominator. For product pricing, gross margin is generally the most relevant comparison with markup.
Follow these steps:
- Determine the selling price.
- Subtract the applicable product cost.
- Divide the resulting profit by the selling price.
- Multiply by 100.
Profit Margin Example
Suppose a product costs $120 and sells for $180.
Gross Margin = $180 – $120 / $180 * 100
= $60 / $180 * 100 = 33.33%
The business earns $60 in gross profit, equivalent to a 33.33% gross margin.
This example demonstrates why a 50% markup does not produce a 50% gross margin.
How to Convert Markup to Margin
Businesses often calculate a markup percentage first and then need to determine the corresponding gross margin. You can convert between the two without knowing the original dollar cost.
The formula for converting markup to margin is:
Margin=Markup1+Markup
Use decimal values in this formula.
For example, a 50% markup is represented as 0.50:
0.50 / 1.50 * 100 = 33.33%
Therefore, a 50% markup corresponds to a 33.33% gross margin.
How to Convert Margin to Markup
If you know your target gross margin and need to calculate the required markup, use:
Markup=Margin1-Margin
For example, a 40% target gross margin is represented as 0.40:
0.40 / 1 – 0.40 * 100 = 66.67%
You need a 66.67% markup on cost to achieve a 40% gross margin, assuming the cost and selling price are defined consistently.
These conversion formulas are useful when switching between a pricing strategy based on cost and a financial target based on revenue.
Markup vs Margin Conversion Table
The following table shows how different markup percentages translate into gross margins.
| Markup | Equivalent gross margin |
| 10% | 9.09% |
| 20% | 16.67% |
| 25% | 20% |
| 30% | 23.08% |
| 40% | 28.57% |
| 50% | 33.33% |
| 60% | 37.50% |
| 75% | 42.86% |
| 100% | 50% |
| 150% | 60% |
| 200% | 66.67% |
These percentages assume a positive product cost, a selling price above that cost, and no additional deductions from gross profit.
How to Set Product Prices Using Markup and Margin
Choosing the right selling price requires more than adding a percentage to the purchase cost. Businesses must consider their expenses, customers, competitors, and financial goals.
The following steps can help US small businesses develop a more reliable pricing strategy.
1. Calculate the Full Cost of Your Product
Start by identifying the costs associated with acquiring or producing the product.
Depending on your business, these may include:
- Purchase price or manufacturing cost
- Raw materials and direct labor
- Freight and inbound shipping
- Import duties and other applicable charges
- Packaging and labeling
- Other costs properly attributable to inventory
For an e-commerce business, you should also evaluate selling expenses such as payment processing, fulfillment, outbound shipping subsidies, returns, and advertising.
Not every expense belongs in inventory cost under generally accepted accounting principles (GAAP). Keep inventory costing consistent with the accounting method applicable to your business, and account for operating expenses separately when appropriate.
The IRS Small Business Tax Guide explains how businesses calculate cost of goods sold and gross profit for federal tax purposes.
2. Choose Your Target Gross Margin
Decide how much of your selling revenue should remain after deducting the applicable cost of the product.
For example, suppose your product cost is $40 and you want a 35% gross margin.
Use this formula:
SellingPrice=Cost1-TargetMargin
Selling Price = $40 / 1 – 0.35 = $61.54
You would need to charge approximately $61.54 to achieve a 35% gross margin before other expenses.
3. Research Competitor Pricing
A mathematically correct price is not necessarily competitive. Research similar products, customer expectations, product quality, delivery options, and your brand’s positioning.
The US Small Business Administration recommends market research and competitive analysis to understand demand, competing offers, and what customers are willing to pay.
Avoid choosing a markup percentage solely because another retailer uses it. Different businesses have different costs, sales volumes, and operating models.
4. Account for Operating Expenses
A product can have a healthy gross margin while the business still loses money.
For example, assume your monthly fixed operating expenses are $6,000 and your average contribution per unit is $20 after variable costs.
Break-Even Units = $6,000 / $20 = 300
You must sell 300 units per month to cover the $6,000 in fixed expenses under these assumptions.
Contribution per unit is not always the same as gross profit per unit. If selling fees, shipping subsidies, or advertising vary with sales, include those variable costs when calculating contribution.
The SBA’s business planning and break-even guidance provides additional information on startup costs, pricing, and break-even analysis.
5. Review Prices Regularly
Supplier prices, shipping rates, labor costs, advertising expenses, and customer demand can change over time. Review your product costs and margins periodically.
Track the following metrics:
- Average selling price
- Cost of goods sold
- Gross profit
- Gross margin percentage
- Contribution margin
- Return and refund rates
- Sales volume and break-even point
Maintaining accurate sales, purchase, and expense records also helps you monitor financial performance and prepare US federal tax returns.
Common Markup vs Margin Mistakes to Avoid
Confusing markup with gross margin
Adding a 40% markup does not create a 40% gross margin. If the product cost is $100, a 40% markup produces a $140 selling price and a gross margin of approximately 28.57%.
Always confirm which percentage a pricing target refers to.
Forgetting business expenses
The difference between the selling price and product cost is not necessarily net profit. Advertising, payroll, rent, payment processing, and other expenses may significantly reduce the amount the business ultimately retains.
Applying the same markup to every product
Different products can have different costs, demand levels, return rates, and competitive pressures. A single markup may work for some items but produce unsuitable prices for others.
Use product-level cost and margin analysis to make better decisions.
Ignoring discounts and returns
A product listed for $100 may generate only $90 in revenue after a $10 discount. If its cost remains $60, the gross profit is $30 and the gross margin on the discounted selling price is 33.33%.
Calculate profitability using actual net sales rather than relying exclusively on the original list price.
Assuming gross margin equals net profit
Gross margin excludes many expenses that affect overall profitability. Net profit margin accounts for a broader range of costs, including operating expenses and other applicable items.
Understand which measure you are calculating before using it in a business report.
Markup vs Margin for Different Types of Businesses
Retail businesses
Retailers use markup to set shelf prices and gross margin to evaluate how effectively sales cover the cost of merchandise. Inventory shrinkage, markdowns, and returns can affect actual results.
E-commerce businesses
Online sellers should evaluate product costs alongside fulfillment, payment processing, shipping subsidies, refunds, and advertising. A high markup does not guarantee a profitable online order.
Manufacturers and wholesalers
Manufacturers need to consider raw materials, production labor, manufacturing overhead, packaging, and other relevant production costs. Wholesalers may use different pricing structures for bulk orders, distributors, and direct customers.
Service businesses
Consultants, freelancers, and agencies can use similar pricing principles, but their cost structures differ from those of product sellers. Labor time, subcontractors, software, insurance, and overhead may be important pricing inputs.
For service businesses, gross margin calculations depend on how direct service-delivery costs are defined and recorded.
US Pricing and Accounting Considerations
Markup and margin are financial calculations rather than standalone legal or tax requirements. However, the underlying pricing and accounting records matter for US businesses.
Keep these considerations in mind:
- Federal tax reporting: Maintain accurate records of business income, purchases, inventory, and deductible expenses. Follow the IRS rules applicable to your business structure and accounting method.
- Sales tax: Sales tax is separate from markup and profit margin. State and local requirements vary, and the applicable tax treatment depends on the transaction and jurisdiction.
- Advertising and pricing claims: If you advertise discounts, savings, or comparative prices, ensure your claims are truthful and not misleading. Review applicable federal and state consumer protection requirements.
- Financial reporting: Use consistent cost definitions when comparing gross margins across products or reporting periods.
For authoritative information, consult the IRS, the US Small Business Administration, and the Federal Trade Commission.
This article provides general educational information, not individualized accounting, legal, or tax advice.
Frequently Asked Questions (FAQs)
1. What is the main difference between markup and margin?
Markup measures profit as a percentage of cost, whereas gross margin measures profit as a percentage of selling price. They use the same dollar profit but different denominators.
2. Is a 30% markup the same as a 30% margin?
No. A 30% markup produces a gross margin of approximately 23.08%, assuming the markup is applied to the full cost used in the calculation.
3. What markup do I need for a 40% gross margin?
You need a markup of approximately 66.67% to achieve a 40% gross margin.
For example, if your cost is $60, divide $60 by 0.60 to get a selling price of $100. The resulting gross profit is $40.
4. Can markup be higher than 100%?
Yes. A 100% markup means the markup amount equals the product cost. If a product costs $50, a 100% markup produces a $100 selling price.
A markup above 100% is also possible when the markup amount exceeds the original cost.
5. Can a business have a high markup but a low net profit margin?
Yes. A high markup can produce a strong gross profit per product, but operating expenses, advertising costs, payroll, rent, and other expenses can substantially reduce net profit.
6. Should I use markup or margin to price products?
Use markup as a convenient way to calculate a price from cost. Use gross margin to evaluate how much of your sales revenue remains after the applicable product costs.
For better pricing decisions, calculate both and review your operating expenses.
7. How do you calculate markup in Excel?
If cell A2 contains the product cost and cell B2 contains the selling price, enter this formula:
=(B2-A2)/A2
Format the result as a percentage. Make sure the cost in A2 is greater than zero.
8. How do you calculate gross margin in Excel?
If A2 contains the product cost and B2 contains the selling price, enter:
=(B2-A2)/B2
Format the result as a percentage. This calculates gross margin using the same cost and price assumptions.
9. Does markup include sales tax?
Markup is normally calculated using the business’s cost and selling price before separately collected sales tax. Sales tax treatment varies by jurisdiction, so consult the applicable state and local rules.
10. What is the difference between gross margin and net profit margin?
Gross margin measures gross profit relative to revenue after deducting the applicable cost of goods sold. Net profit margin measures net profit relative to revenue after accounting for a broader range of business expenses and other applicable items.
Conclusion
Understanding markup vs margin helps business owners set more accurate prices, measure product profitability, and avoid common pricing errors.
Markup is based on cost, making it useful when establishing selling prices. Gross margin is based on revenue, making it useful for evaluating product-level profitability and comparing financial performance.
For example, a product that costs $60 and sells for $100 has a 66.67% markup and a 40% gross margin. Both percentages describe the same $40 difference, but they answer different financial questions.
For the best results, calculate both metrics, include relevant costs in your pricing analysis, review competitor prices, and monitor operating expenses. Consistent accounting records and regular financial reviews will help you make more informed pricing decisions as your business grows.
References
The following authoritative resources support the article’s US business, accounting, and pricing guidance.
| Resource | Recommended anchor text | Purpose |
| IRS Publication 334 | IRS Small Business Tax Guide | Cost of goods sold and gross profit |
| IRS Recordkeeping Guide | IRS business recordkeeping requirements | Income, purchases, and expense records |
| U.S. Small Business Administration | Small business pricing and break-even planning | Startup costs, pricing, and financial planning |
| Federal Trade Commission | FTC consumer protection guidance | Truthful advertising and pricing claims |