Introduction
Pricing products correctly is one of the most important decisions a business owner makes. Set prices too low, and you may struggle to cover operating expenses. Set them too high without offering sufficient value, and customers may choose a competitor. A markup calculator helps businesses find a starting selling price by applying a percentage increase to a product’s cost.
Whether you run an online store, retail shop, wholesale business, or small manufacturing company in the United States, understanding markup can help you price products more consistently and evaluate profitability.
However, markup is not the same as profit margin. A 50% markup does not mean that 50% of the selling price is profit. You must also consider operating expenses, shipping, payment processing fees, discounts, returns, and applicable taxes.
This guide explains how a markup calculator works, the formulas behind it, practical pricing examples, and best practices for setting product prices in the US market.
What Is a Markup Calculator?
A markup calculator is a tool that calculates a product’s selling price based on its cost and a chosen markup percentage.
Markup represents the amount added to the cost of a product to establish its selling price. Businesses use it to help cover product costs, contribute toward operating expenses, and generate a profit.
For example, suppose you purchase a product for $40 and apply a 50% markup.
- Product cost: $40
- Markup percentage: 50%
- Markup amount: $20
- Selling price: $60
The calculation is straightforward, but selecting the correct markup requires more thought. A business must account for its cost structure, customer demand, competitors, and profit objectives.
A markup calculator makes the arithmetic faster and reduces the risk of pricing errors. It does not automatically determine the best price for your market.
How to Calculate Markup
The standard markup formula calculates markup as a percentage of cost.
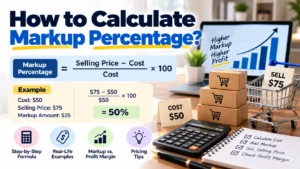
Markup Percentage Formula:
Markup Percentage = (Selling Price − Cost) ÷ Cost × 100
To calculate the selling price from a known cost and target markup, use:
Selling Price = Cost × (1 + Markup Percentage ÷ 100)
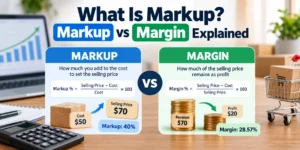
Example: Calculate a 40% Markup
Suppose a retailer purchases a product for $50 and wants to apply a 40% markup.
Step 1: Calculate the markup amount.
$50 × 40% = $20
Step 2: Add the markup to the cost.
$50 + $20 = $70
The selling price is $70.
The retailer has a $20 difference between the selling price and product cost. That amount is not necessarily net profit because it may need to cover other business expenses.
A markup calculator performs these steps automatically once you enter the cost and markup percentage.
Markup Calculator Examples
The following examples show how different markup percentages affect selling prices.
| Product cost | Markup | Markup amount | Selling price |
| $20 | 25% | $5 | $25 |
| $40 | 50% | $20 | $60 |
| $60 | 30% | $18 | $78 |
| $100 | 40% | $40 | $140 |
| $150 | 60% | $90 | $240 |
These examples assume the stated product cost is the base used for the calculation. If you exclude shipping, packaging, production labor, or other relevant costs from that base, your calculated price may be too low to support your business.
For a more complete pricing decision, calculate your relevant unit costs before applying a markup.
Markup vs. Profit Margin: What Is the Difference?
Markup and profit margin are closely related, but they measure profitability from different perspectives.
- Markup measures the increase over cost.
- Profit margin measures the difference between selling price and cost as a percentage of selling price.
Confusing these two metrics can lead to underpricing.
Markup Formula
Markup Percentage = (Selling Price − Cost) ÷ Cost × 100
Profit Margin Formula
Gross Profit Margin = (Selling Price − Cost) ÷ Selling Price × 100
Example: 50% Markup vs. 50% Margin
Suppose a product costs $100.
With a 50% markup:
- Cost: $100
- Markup: $50
- Selling price: $150
- Gross margin: $50 ÷ $150 × 100 = 33.33%
A 50% markup produces a gross margin of approximately 33.33%, not 50%.
Now suppose you want a 50% gross margin instead. You must calculate the selling price differently:
Selling Price = Cost ÷ (1 − Target Margin)
$100 ÷ (1 − 0.50) = $200
The selling price must be $200 to achieve a 50% gross margin on a $100 cost, before other expenses.
The Massachusetts government guide to calculating costs and setting prices explains the difference between markup and margin with practical examples.
How to Calculate a Selling Price From a Target Margin
Some businesses set pricing targets using gross margin rather than markup. If your goal is a particular gross margin, use the margin formula to determine the required selling price.
Selling Price = Product Cost ÷ (1 − Target Margin)
Convert the target margin percentage into a decimal before calculating.
For example, a business has a product cost of $80 and wants a 40% gross margin.
$80 ÷ (1 − 0.40) = $133.33
The required selling price is approximately $133.33.
The gross profit before other expenses is:
$133.33 − $80 = $53.33
This method is particularly useful when a business needs to maintain a consistent gross margin across products with different costs.
Remember that gross margin is not the same as net profit margin. Gross profit generally excludes operating expenses such as rent, marketing, administrative payroll, and some other costs.
How to Choose the Right Markup Percentage
There is no universal markup percentage that works for every business. The right percentage depends on the product, industry, cost structure, competition, customer expectations, and sales channel.
1. Calculate Your Total Unit Cost
Start by identifying the costs associated with acquiring or producing each product.
Depending on your business, these may include:
- Wholesale purchase price or raw materials.
- Direct production labor.
- Packaging and labeling.
- Freight and inbound shipping.
- Manufacturing costs allocated per unit.
- Other directly attributable costs.
For an online retailer, payment processing, fulfillment, and shipping subsidies may also affect the economics of each sale. Some expenses are variable selling costs rather than inventory cost for accounting purposes, so keep the categories distinct when calculating gross margin and overall profitability.
2. Account for Operating Expenses
A selling price must help cover more than the product itself. Businesses may also have rent, utilities, insurance, salaries, software subscriptions, advertising, and other overhead expenses.
For example, a product that costs $30 and sells for $45 generates $15 before subtracting additional costs. If fulfillment, payment fees, and allocated overhead absorb most of that amount, the product may contribute very little toward net profit.
The US Small Business Administration’s business planning resources explain how costs, selling prices, and break-even analysis support business planning.
3. Research Competitor Prices
Compare similar products in your target market. Consider quality, features, delivery speed, warranties, customer service, and brand positioning rather than comparing price alone.
If your price is higher than competitors’, you need to understand whether your product offers a meaningful advantage. If your price is lower, verify that your margin can support the business over time.
Competitor pricing is useful context, but it should not replace your own cost calculations.
4. Consider Customer Demand
Customers do not make purchasing decisions based only on cost. They may pay more for convenience, distinctive design, quality, reliability, or a trusted brand.
Test pricing where practical, monitor conversion rates and sales volume, and assess whether a price change improves total contribution rather than simply increasing revenue per order.
5. Review Your Prices Regularly
Supplier prices, freight rates, labor costs, and advertising expenses can change. Review your cost assumptions regularly and update prices when necessary.
A markup calculator can make these revisions easier because you can recalculate selling prices when costs or target percentages change.
Markup Pricing for US Online Stores
US e-commerce businesses often have costs beyond the purchase price of an item. A price that appears profitable using the wholesale cost alone may not generate the expected return after fulfillment, payment processing, returns, and advertising.
Consider a product with the following illustrative costs:
| Cost component | Amount per unit |
| Wholesale purchase cost | $25.00 |
| Inbound freight and packaging | $3.00 |
| Fulfillment expense | $4.00 |
| Payment processing estimate | $2.00 |
| Total listed costs | $34.00 |
If the business uses $34 as its pricing cost base and applies a 50% markup, the selling price would be:
$34 × 1.50 = $51
The $17 difference between $51 and $34 is not net profit. The business may still need to cover advertising, returns, customer service, software, taxes on income, and other operating expenses.
For accounting purposes, not every cost in this example will necessarily be classified as cost of goods sold. The appropriate accounting classification depends on the business and applicable accounting principles. The example simply demonstrates how additional per-unit expenses affect pricing decisions.
How Sales Tax Affects Product Pricing in the USA
US businesses should distinguish between their product price and any sales tax collected from customers.
Sales tax rules vary by state and, where applicable, local jurisdiction. Whether a transaction is taxable, what rate applies, and whether a seller must collect tax depend on the relevant laws and the seller’s circumstances.
For example, a retailer may list a product for $50 and collect applicable sales tax at checkout. If the applicable tax rate is 7%, the customer would pay $53.50 in total, assuming the full $50 price is taxable and no exemptions or other adjustments apply.
The $3.50 tax collected is generally not business revenue; it is collected for remittance according to the applicable rules.
Do not treat sales tax collected from customers as markup or profit. Also, do not assume that every product or service is taxed the same way in every state.
Consult the relevant state revenue department. For example, the Texas Comptroller’s sales and use tax guidance explains the state’s sales tax framework, including state and local rates.
Common Markup Calculation Mistakes
Even a simple markup formula can produce misleading results if the underlying assumptions are incorrect.
Using Markup and Margin Interchangeably
A 40% markup is not the same as a 40% gross margin. Always confirm which metric you are targeting.
Ignoring Relevant Costs
If you calculate markup only on the supplier’s price, you may overlook freight, packaging, or other costs that affect the economics of the sale.
Assuming Markup Equals Net Profit
The difference between selling price and product cost may need to cover operating expenses. Net profit is calculated only after all relevant expenses are accounted for.
Copying Competitors Without Calculating Your Own Costs
A competitor may have different supplier terms, purchasing volume, fulfillment arrangements, or overhead. A price that works for one company may not work for another.
Forgetting Discounts and Returns
Promotional discounts reduce the amount of revenue retained from a sale. Returns can create additional shipping, handling, restocking, or inventory losses. Include realistic assumptions when evaluating profitability.
Best Practices for Pricing Products Like a Pro
To use a markup calculator effectively, follow a consistent pricing process:
- Verify your costs: Use current supplier prices and realistic per-unit cost assumptions.
- Choose your target: Decide whether you are setting a markup percentage or targeting a gross margin.
- Calculate the initial price: Apply the appropriate formula or use a markup calculator.
- Evaluate market conditions: Compare the price with similar products and customer expectations.
- Check profitability: Account for discounts, variable selling costs, and overhead where appropriate.
- Monitor results: Track sales volume, returns, contribution, and gross margin.
- Recalculate when costs change: Update prices when supplier or operating costs shift.
The goal is not simply to select the highest markup. It is to set a price that supports profitability while remaining appropriate for the product and market.
Frequently Asked Questions
What is a markup calculator used for?
A markup calculator helps businesses determine the markup amount and selling price based on a product’s cost and a selected markup percentage. It can also support price comparisons and cost updates.
What is the formula for markup?
The formula is:
Markup Percentage = (Selling Price − Cost) ÷ Cost × 100
To calculate the selling price from cost and markup:
Selling Price = Cost × (1 + Markup Percentage ÷ 100)
Is a 50% markup good?
It depends on your business and cost structure. A 50% markup produces a gross margin of approximately 33.33% when the markup is applied to the same cost used in the margin calculation. Whether that is sufficient depends on operating expenses, customer demand, competition, and profit goals.
What is the difference between markup and margin?
Markup measures the difference between selling price and cost as a percentage of cost. Margin measures that difference as a percentage of selling price. Margin is usually lower than markup for the same positive-profit sale.
Should sales tax be included in a markup calculation?
Sales tax collected from customers should generally be treated separately from product revenue and markup. Apply the relevant state and local tax rules to determine whether tax must be collected and how it should be reported.
Can a markup calculator guarantee a profit?
No. A markup calculator performs arithmetic based on the inputs you provide. It cannot guarantee sales, account for every business expense automatically, or predict customer demand. Profitability depends on actual costs, sales volume, returns, operating expenses, and other business factors.
Conclusion
A markup calculator is a practical tool for setting initial selling prices, comparing markup percentages, and responding to cost changes. By understanding the difference between markup and margin, US businesses can avoid common pricing errors and make better-informed decisions.
Start with accurate cost information, choose a clear pricing target, and evaluate your price against customer demand and competitors. Remember to account for operating expenses, discounts, returns, and applicable sales tax rules.
Use the CalcZest Markup Calculator to calculate a starting selling price, then review the result against your full cost structure and business goals.
Disclaimer: This article is for general educational purposes only and does not constitute accounting, tax, legal, or financial advice. Business costs, accounting classifications, and sales tax obligations vary. Consult qualified professionals for advice specific to your business.