An employee stock purchase plan (ESPP) allows eligible employees to purchase company shares, often at a discount through payroll deductions. This benefit can help employees build an ownership stake in their employer, but selling those shares creates tax questions that are not always straightforward.
The most important factor in ESPP tax treatment is how long you hold the shares before selling them. If you meet the IRS holding period requirements, your sale generally qualifies for favorable tax treatment under Section 423 of the Internal Revenue Code. If you sell before meeting those requirements, the transaction becomes a disqualifying disposition.
Both types of sales can involve ordinary income and capital gains or losses. However, the amount you report as compensation and the way you calculate your adjusted cost basis can differ.
For example, an employee who buys shares for $85 when their fair market value is $100 may have a $15 purchase discount. If the employee later sells the shares, the IRS rules determine whether that discount creates ordinary income and how much of the remaining profit qualifies as a capital gain.
This guide explains how ESPP shares are taxed when you sell, how qualifying and disqualifying dispositions work, how to calculate your taxable gain, and how to report the transaction correctly on your US federal tax return.
What Is an Employee Stock Purchase Plan (ESPP)?
An employee stock purchase plan is an employer-sponsored benefit that allows employees to buy company stock under specific plan rules.
Many ESPPs let employees contribute a percentage of their salary through payroll deductions. The employer accumulates those contributions during an offering period and uses the money to purchase company shares on a designated purchase date.
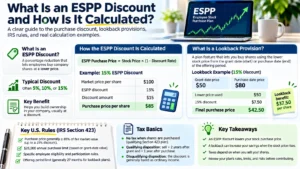
Some Section 423 ESPPs offer shares at a discount, often up to 15% below the applicable fair market value. Certain plans also include a lookback provision, which uses the lower stock price on the offering date or purchase date to calculate the employee’s purchase price.
For example:
- Stock price on offering date: $100
- Stock price on purchase date: $120
- ESPP discount: 15%
- Purchase price using the lower offering-date price: $85
The employee purchases shares for $85 even though the market price on the purchase date is $120.
The difference between the purchase price and market value represents an economic benefit. However, the federal tax treatment depends on the type of ESPP and when the employee sells the shares.
Important: This article primarily covers qualified ESPPs under Section 423. Nonqualified employee stock purchase arrangements can follow different tax rules.
You can review the IRS guidance on employee stock purchase plans for more information.
When Do You Pay Taxes on ESPP Shares?
For a qualified Section 423 ESPP, you generally do not include income when your employer grants the option or when you exercise it to purchase shares.
Instead, you generally recognize taxable income when you sell or otherwise dispose of the shares.
At that point, the tax treatment depends on whether you meet the required holding period.
There are two main categories:
- Qualifying disposition: You meet both required holding periods.
- Disqualifying disposition: You sell before meeting at least one required holding period.
Both categories can create ordinary income and capital gain or loss. The difference is how the IRS calculates the ordinary income component.
This distinction matters because ordinary income generally receives the tax treatment of compensation, while capital gains may qualify for short-term or long-term capital gains tax rates.
What Is a Qualifying Disposition?
A qualifying disposition occurs when you hold ESPP shares long enough to satisfy both IRS holding period requirements under Section 423.
You must avoid selling the shares until the end of the later of:
- The one-year period after the shares were transferred to you.
- The two-year period after the option grant date.
In many ESPPs, the grant date corresponds to the beginning of the offering period. However, you should verify the actual grant date in your plan documents and Form 3922 rather than assuming every plan uses the same terminology.
Qualifying Disposition Example
Suppose your employer offers a qualified ESPP with these details:
| Description | Amount |
| Fair market value on grant date | $100 |
| Purchase price | $85 |
| Fair market value on purchase date | $100 |
| Sale price after required holding periods | $130 |
| Number of shares sold | 100 |
Your total purchase cost is:
100 × $85 = $8,500
Your sale proceeds are:
100 × $130 = $13,000
Your total economic gain is:
$13,000 − $8,500 = $4,500
However, the IRS divides the gain into ordinary income and capital gain.
For a qualifying disposition, ordinary income generally equals the lesser of:
- The fair market value on the grant date minus the option purchase price, multiplied by the shares sold.
- The sale price minus the purchase price, multiplied by the shares sold.
In this example:
Grant-date discount:
($100 − $85) × 100 = $1,500
Actual gain:
($130 − $85) × 100 = $4,500
The ordinary income amount is the lower figure: $1,500.
The remaining gain is capital gain:
$4,500 − $1,500 = $3,000
| Tax Component | Amount |
| Total gain | $4,500 |
| Ordinary income | $1,500 |
| Capital gain | $3,000 |
The employee generally reports the $1,500 as compensation income and the $3,000 as capital gain.
The capital gain may qualify for long-term capital gains tax treatment if the employee also meets the applicable capital asset holding period requirements.
Why is this treatment beneficial?
A qualifying disposition can limit the ordinary income portion to the grant-date discount, even if the stock price increases significantly before the employee sells.
The remaining appreciation may qualify for long-term capital gains treatment.
See IRS Publication 525 – Employee Stock Purchase Plans for the official calculation rules.
What Is a Disqualifying Disposition?
A disqualifying disposition occurs when you sell ESPP shares before completing both required holding periods.
You do not necessarily lose the economic benefit of your ESPP discount. However, the IRS generally treats a different amount as ordinary compensation income.
For a typical Section 423 ESPP, ordinary income generally equals the difference between:
- The fair market value of the shares on the exercise or purchase date.
- The amount you paid for the shares.
You then calculate capital gain or loss using an adjusted basis that includes the ordinary income amount.
Disqualifying Disposition Example
Suppose you participate in an ESPP with these details:
| Description | Amount |
| Fair market value on grant date | $100 |
| Fair market value on purchase date | $120 |
| Purchase price | $85 |
| Sale price | $135 |
| Number of shares | 100 |
Your purchase cost is:
100 × $85 = $8,500
Your sale proceeds are:
100 × $135 = $13,500
Total economic gain:
$13,500 − $8,500 = $5,000
Because you sell before meeting the required holding periods, the sale is a disqualifying disposition.
Calculate ordinary income:
($120 − $85) × 100 = $3,500
The adjusted tax basis becomes:
$8,500 + $3,500 = $12,000
Now calculate the capital gain:
$13,500 − $12,000 = $1,500
| Tax Component | Amount |
| Total economic gain | $5,000 |
| Ordinary income | $3,500 |
| Capital gain | $1,500 |
| Adjusted cost basis | $12,000 |
The employee generally reports $3,500 as ordinary compensation income and $1,500 as capital gain.
Because the employee sold before meeting the required ESPP holding periods, the ordinary income portion is generally reported as wages, while the capital gain or loss receives the applicable capital gains treatment.
Qualifying vs. Disqualifying Disposition: Key Differences
The main difference is the amount of ordinary income you recognize when you sell the shares.
| Feature | Qualifying Disposition | Disqualifying Disposition |
| Holding period | Meets both IRS requirements | Fails at least one requirement |
| Ordinary income calculation | Generally the lesser of grant-date discount or actual gain | Generally purchase-date FMV minus purchase price |
| Capital gain or loss | Sale proceeds minus adjusted basis | Sale proceeds minus adjusted basis |
| Potential capital gains treatment | Remaining gain may qualify as long-term | Depends on the separate capital asset holding period |
| Main advantage | May limit ordinary income | Does not meet the special Section 423 holding period |
A qualifying disposition does not make the entire profit tax-free. It changes how the IRS divides the gain between ordinary income and capital gain.
A disqualifying disposition does not mean you automatically pay tax on the entire sale proceeds. You report the compensation component and calculate the remaining capital gain or loss using an adjusted basis.
How Does the ESPP Discount Affect Your Taxes?
The ESPP discount is an important part of the tax calculation.
Many qualified ESPPs allow employees to buy shares at a discount, often up to 15%. Some plans also include a lookback provision.
A lookback provision can calculate the purchase price using the lower stock value on the grant date or purchase date.
For example:
| Description | Amount |
| Stock price on grant date | $100 |
| Stock price on purchase date | $120 |
| Discount | 15% |
| Purchase price | $85 |
The purchase price is:
$100 × (1 − 0.15) = $85
Although the stock trades at $120 on the purchase date, the employee pays $85.
The resulting discount and any additional market appreciation affect the ordinary income and capital gain calculations differently depending on the disposition type.
Does a 15% ESPP Discount Always Mean 15% Ordinary Income?
No. The discount percentage alone does not determine your final ordinary income.
For a qualifying disposition, the calculation generally uses the grant-date fair market value and the actual gain at sale.
For a disqualifying disposition, the calculation generally uses the fair market value on the purchase date and the purchase price.
A lookback provision can also affect the option price and the amount treated as compensation.
Always use the actual values and dates from your plan records.
What Happens If You Sell ESPP Shares at a Loss?
You may still have ordinary income from a disqualifying disposition even when the stock price falls after purchase.
This is one of the most important ESPP tax details for employees.
Consider this example:
- Purchase-date fair market value: $100
- Purchase price: $85
- Sale price: $80
- Shares sold: 100
The employee paid:
100 × $85 = $8,500
The employee received:
100 × $80 = $8,000
Economic loss:
$8,000 − 8,500=-500
However, because the employee made a disqualifying disposition, ordinary income generally equals:
($100 − $85) × 100 = $1,500
The adjusted basis becomes:
$8,500 + $1,500 = $10,000
Capital loss:
$8,000 − 10,000=-2,000
| Tax Component | Amount |
| Purchase cost | $8,500 |
| Sale proceeds | $8,000 |
| Ordinary income | $1,500 |
| Adjusted tax basis | $10,000 |
| Capital loss | $2,000 |
This example shows why ESPP tax reporting can look unusual: the employee has an economic loss of $500 but may still report $1,500 of ordinary income and a $2,000 capital loss.
The capital loss may offset capital gains and, subject to the applicable rules, a limited amount of ordinary income. Capital loss carryforward rules may apply if losses exceed the permitted annual deduction.
Review IRS Topic No. 409 – Capital Gains and Losses for more information.
How Is ESPP Cost Basis Calculated?
Cost basis is the amount you use to calculate your capital gain or loss when selling shares.
For ESPP shares, the cost basis can become confusing because the purchase price shown by your broker may not include the compensation income you must report.
If you report ordinary income from an ESPP sale, you generally add that amount to your original purchase cost to calculate your adjusted basis.
Adjusted ESPP Basis = Purchase Price + Ordinary Income Recognized
For example:
- Purchase price: $8,500
- Ordinary income: $1,500
- Adjusted basis: $10,000
If you sell the shares for $13,000:
$13,000 − $10,000 = $3,000 capital gain
Without the basis adjustment, you might incorrectly report the entire $4,500 difference as capital gain, even though $1,500 already qualifies as ordinary compensation income.
This can cause double taxation.
Why Can Form 1099-B Show the Wrong ESPP Cost Basis?
Your broker generally reports stock sale proceeds on Form 1099-B. However, the basis shown on the form may not include the compensation income that you must recognize under the ESPP rules.
As a result, the reported basis may be lower than your correct adjusted tax basis.
You must review the information and make any required adjustment when reporting the sale on Form 8949.
The IRS specifically warns taxpayers that they may need to adjust basis information reported on Form 1099-B.
See IRS Publication 525 and the IRS stock option reporting FAQ.
How to Report ESPP Shares on Your US Tax Return
When you sell ESPP shares, you may need to report both ordinary compensation income and capital gain or loss.
The exact reporting depends on whether the sale qualifies under Section 423 and whether your employer includes the compensation amount in Form W-2.
The main tax documents include:
1. Form 3922
Your employer generally provides Form 3922 when it records the first transfer of legal title of shares acquired through a qualifying Section 423 ESPP under the applicable reporting requirements.
The form contains information you need to calculate the holding period and cost basis.
Important boxes include:
| Form 3922 Box | Information |
| Box 1 | Option grant date |
| Box 2 | Option exercise date |
| Box 3 | Fair market value on grant date |
| Box 4 | Fair market value on exercise date |
| Box 5 | Exercise price per share |
| Box 6 | Number of shares transferred |
| Box 7 | Date legal title was transferred |
| Box 8 | Additional option price information, when applicable |
Keep Form 3922 with your tax records. You generally do not attach it to your federal income tax return.
Official source: IRS – About Form 3922.
2. Form W-2
Your employer or former employer generally reports the ordinary income from an ESPP sale as wages in Box 1 of Form W-2.
For a qualifying disposition, the ordinary income amount generally follows the Section 423 calculation.
For a disqualifying disposition, the ordinary income generally reflects the purchase-date discount.
If the employer does not report the required amount in Box 1, the IRS provides instructions for reporting the amount on Schedule 1, Form 1040, line 8k.
Do not assume that your employer has reported the correct amount automatically. Compare the W-2 with your ESPP transaction records.
3. Form 1099-B
Your broker generally issues Form 1099-B after you sell shares.
It reports important information, including:
- Sale proceeds
- Acquisition date
- Cost basis, when reportable
- Whether the sale is short-term or long-term
- Other applicable transaction information
The basis may not include ESPP compensation income, so you should not automatically accept the broker’s basis as your final adjusted basis.
4. Form 8949 and Schedule D
You generally report the stock sale on Form 8949 and Schedule D.
Form 8949 provides transaction-level details, including proceeds, cost basis, and adjustments.
Schedule D summarizes capital gains and losses from the transactions.
The ordinary income component must also appear in the appropriate income section of your tax return.
Practical checklist before filing:
- Collect Form 3922.
- Obtain Form 1099-B from your broker.
- Check Form W-2 for ESPP compensation income.
- Identify the grant date and transfer date.
- Determine whether the sale qualifies.
- Calculate the adjusted cost basis.
- Report the sale on Form 8949 and Schedule D.
- Check that you do not report the same compensation income twice.
Short-Term vs. Long-Term Capital Gains on ESPP Shares
The ESPP qualifying disposition holding period and the general capital gains holding period are related, but they are not identical.
To receive qualifying disposition treatment under Section 423, you must satisfy both the one-year-after-transfer and two-years-after-grant requirements.
Separately, the general capital gains rules classify a capital asset held for more than one year as a long-term asset. An asset held for one year or less generally produces a short-term capital gain or loss.
For ESPP shares, the holding period for the stock generally begins the day after the option exercise date.
This distinction matters because a sale can be a disqualifying disposition under the ESPP rules but still produce a long-term capital gain on the portion treated as capital gain if the stock itself has been held for more than one year.
For example, an employee may sell shares more than one year after purchase but before the two-year grant-date requirement has passed. The sale remains disqualifying, even though the capital gain portion may qualify as long-term.
Review IRS Topic No. 409 – Capital Gains and Losses for the general holding period rules.
What Happens If You Sell ESPP Shares Immediately?
Some employees sell ESPP shares as soon as the company transfers them to their brokerage account.
This is commonly called a same-day sale or immediate sale.
A same-day sale generally creates a disqualifying disposition because the employee has not met the required holding periods.
For a typical discounted Section 423 ESPP, the difference between the purchase-date fair market value and the purchase price generally becomes ordinary income.
The employee may also have a small capital gain or loss depending on the difference between the actual sale price and the purchase-date fair market value.
For example:
- Purchase price: $85
- Purchase-date market value: $100
- Immediate sale price: $100
Ordinary income:
$100 − $85 = $15 per share
Capital gain or loss:
100-(85 + $15) = $0
This example assumes the sale occurs at the same market price used for the purchase-date valuation and excludes transaction costs.
Immediate sales can reduce exposure to future stock price changes, but they do not provide qualifying disposition treatment.
Should You Hold ESPP Shares to Get Qualifying Tax Treatment?
Holding shares long enough to qualify may reduce the ordinary income portion and allow more appreciation to receive capital gains treatment.
However, waiting also exposes you to market risk.
Suppose your employer’s stock represents a significant part of your financial situation. You may already depend on the company for your salary, benefits, and future career opportunities.
Holding additional company stock increases that concentration.
Before waiting for a qualifying disposition, consider:
- The stock’s current market value.
- Your required holding period dates.
- The potential ordinary income difference.
- Your personal investment risk tolerance.
- Your need for cash.
- The impact of company performance on your employment and investments.
- Any trading restrictions or blackout periods.
A qualifying disposition may provide favorable tax treatment, but it does not guarantee a better financial outcome.
If the share price falls substantially while you wait, the market loss may outweigh the potential tax benefit.
For many employees, the decision involves balancing tax treatment against investment risk rather than focusing only on the tax rate.
Common ESPP Tax Mistakes to Avoid
1. Selling Before Checking the Holding Period
Selling even one day too early can make a transaction a disqualifying disposition. Confirm both required dates before selling if you want qualifying treatment.
2. Assuming the 15% Discount Is Always Ordinary Income
The ordinary income amount depends on the grant-date and purchase-date values, the option price, and the sale price. A 15% plan discount does not automatically determine the final taxable amount.
3. Using the Form 1099-B Basis Without Reviewing It
Your broker’s basis may not include the compensation income recognized under ESPP rules. Adjust the basis when required.
4. Reporting the Same Income Twice
If your employer already included ESPP compensation in Form W-2, make sure your Form 8949 adjustment prevents you from treating that same amount as additional capital gain.
5. Ignoring a Sale at a Loss
A disqualifying disposition can still create ordinary income even when the stock sells below the purchase price. Calculate both the compensation income and capital loss.
6. Confusing ESPPs With Stock Options
Section 423 ESPPs have their own tax rules. Incentive stock options (ISOs) and nonqualified stock options (NSOs) follow different rules, so do not use their tax calculations interchangeably.
Frequently Asked Questions
1. How are ESPP shares taxed when you sell them?
You may report ordinary income and capital gain or loss. The ordinary income amount depends on whether the sale qualifies under the Section 423 holding period rules. You generally report the stock sale on Form 8949 and Schedule D.
2. What is a qualifying disposition for an ESPP?
A qualifying disposition occurs when you sell shares after satisfying both holding period requirements: the end of the one-year period after the shares were transferred to you and the end of the two-year period after the option grant date.
3. What is a disqualifying disposition?
A disqualifying disposition occurs when you sell ESPP shares before satisfying both required holding periods. The purchase-date discount generally becomes ordinary compensation income, and you calculate any remaining gain or loss using an adjusted cost basis.
4. Is ESPP income taxed as ordinary income or capital gains?
It can be both. The ordinary income portion represents compensation under the applicable ESPP rules. Any remaining gain or loss generally receives capital gains treatment.
5. Do I pay taxes when I purchase ESPP shares?
For a qualified Section 423 ESPP, you generally do not recognize regular federal income when your employer grants the option or when you exercise it to purchase shares. You generally recognize income when you sell or otherwise dispose of the stock.
6. Does Form 1099-B include my ESPP discount?
Not necessarily. Your broker may report the original purchase basis without including the compensation income recognized under the ESPP rules. Review Form 3922 and Form W-2, then adjust the basis on Form 8949 when required.
7. Can I sell ESPP shares immediately?
Yes, subject to your employer’s trading policies and applicable securities laws. However, an immediate sale generally creates a disqualifying disposition because you have not met the required holding periods.
8. What happens if I sell ESPP shares at a loss?
You may report a capital loss. However, a disqualifying disposition can still create ordinary income based on the purchase-date discount. Calculate both amounts separately.
9. Are ESPP shares subject to short-term or long-term capital gains tax?
The capital gain or loss portion follows the general capital asset holding period rules. A holding period of more than one year generally produces long-term capital gain or loss. However, the separate Section 423 qualifying disposition test also requires the two-year grant-date holding period.
10. Do I need Form 3922 to file ESPP taxes?
Form 3922 provides important grant-date, exercise-date, stock value, and transfer information. You should keep it to calculate your holding period and adjusted basis. You generally do not attach it to your tax return.
Conclusion
Understanding ESPP tax treatment is essential before selling shares purchased through an employee stock purchase plan.
The main factor is whether your sale qualifies under the Section 423 holding period requirements. A qualifying disposition generally limits ordinary income to the lesser of the grant-date discount or the actual gain. A disqualifying disposition generally treats the purchase-date discount as ordinary compensation income.
Both situations can also create capital gains or losses, so you must calculate your adjusted cost basis correctly.
Before filing your US federal tax return, review Form 3922, Form W-2, and Form 1099-B. Report the ordinary income and capital transaction in the correct places, and adjust the broker-reported basis when necessary to avoid double taxation.
A qualifying disposition may offer favorable tax treatment, but holding company stock also creates investment risk. Consider both the tax consequences and your overall financial position before deciding when to sell.
Disclaimer: This article provides general educational information and does not constitute tax, legal, or investment advice. ESPP tax treatment depends on the plan’s qualification under Section 423, grant and transfer dates, purchase price, sale price, holding period, and individual tax circumstances. Consult the IRS or a qualified tax professional for advice about your specific transaction.