Introduction
Employee stock ownership and equity compensation can help employees benefit from their company’s success. In the United States, two terms that often appear in discussions about employee ownership are Employee Stock Ownership Plans (ESOPs) and Restricted Stock Units (RSUs).
Although both involve company stock, ESOPs and RSUs are fundamentally different arrangements. An ESOP is generally a qualified retirement plan designed to invest primarily in employer stock. RSUs, on the other hand, are compensation awards that promise to deliver shares or their cash equivalent when specified conditions are met.
Understanding the difference between ESOP vs RSU can help employees evaluate workplace benefits, compare compensation packages, and make more informed financial decisions.
The distinction matters because the two arrangements have different eligibility rules, vesting provisions, tax treatment, access to funds, and financial risks. An ESOP generally operates within the US retirement plan framework, while RSUs are typically part of an employer’s equity compensation program.
This guide explains how each arrangement works, compares their benefits and limitations, and outlines the tax considerations employees should understand.
What Is an ESOP?
An Employee Stock Ownership Plan, or ESOP, is a type of qualified defined contribution retirement plan that invests primarily in the employer’s stock.
According to the Internal Revenue Service (IRS), an ESOP is established under specific provisions of the Internal Revenue Code and must satisfy applicable qualification requirements.
ESOPs are commonly used by businesses that want to give employees an ownership interest while providing a structured retirement benefit.
How Does an ESOP Work?
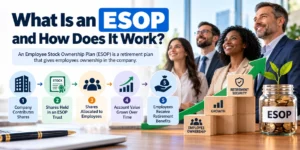
An ESOP generally follows several steps:
- The employer establishes a plan that meets applicable legal requirements.
- The plan acquires employer stock, sometimes using employer contributions or borrowed funds.
- Shares are allocated to participating employees’ accounts under the plan’s terms.
- Employees become entitled to benefits according to the plan’s vesting and distribution provisions.
- Eligible participants receive distributions when permitted under the plan and applicable law.
Employees generally do not purchase the allocated shares directly through ordinary payroll deductions. Instead, the plan holds the stock for participants under its governing documents.
The value of an employee’s ESOP account can increase or decrease as the employer’s stock value changes and as additional shares are allocated.
For example, an employee might have an ESOP account valued at $40,000. If the underlying shares increase in value, the account could become worth more. If the company’s value declines, the account could lose value.
However, an ESOP account balance is not the same as cash available for immediate withdrawal. Distribution rules, vesting, retirement plan restrictions, and applicable tax provisions determine when benefits can be accessed.
What Are Restricted Stock Units (RSUs)?
Restricted Stock Units are a form of employer compensation. An RSU represents a promise to deliver company shares or, under the award’s terms, their cash equivalent after specified conditions are satisfied.
RSUs are common among publicly traded companies and are also used by some private businesses.
Unlike an ESOP, an RSU award is generally not a retirement plan account. It is part of an employee’s compensation arrangement.
How Do RSUs Work?
An RSU award generally follows these steps:
- The employer grants RSUs to an eligible employee.
- The award agreement establishes the vesting schedule and conditions.
- The employee satisfies the applicable requirements, such as remaining employed through a vesting date.
- The vested units are settled in shares or cash according to the award terms.
- The employee may hold or sell delivered shares, subject to applicable restrictions.
Consider an employee who receives 500 RSUs. If all 500 units vest when the company’s stock price is $60 per share, the gross value at settlement is $30,000.
The employee may receive fewer shares than the number vested if some shares are withheld or sold to cover taxes.
The actual value can also change if the share price moves before the employee sells the shares.
RSUs therefore provide a potential compensation benefit, but their value is not guaranteed.
ESOP vs RSU: Key Differences
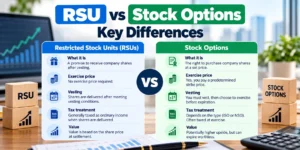
The main difference is that an ESOP is a retirement plan, while RSUs are equity compensation awards.
| Feature | ESOP | RSUs |
| Full name | Employee Stock Ownership Plan | Restricted Stock Units |
| Main purpose | Retirement benefits and employee ownership | Employee compensation and retention |
| Structure | Qualified retirement plan | Equity compensation award |
| Stock ownership | Plan holds employer stock for participants | Shares are generally delivered upon settlement |
| Funding | Typically funded through employer contributions and plan transactions | Granted under an employer compensation program |
| Vesting | Governed by retirement plan rules | Governed by the RSU award agreement |
| Access to value | Subject to plan distribution rules | Generally after vesting and settlement, subject to restrictions |
| Tax treatment | Generally follows qualified retirement plan rules | Generally treated as wage income at settlement |
| Selling shares | Depends on plan structure and distribution provisions | Depends on whether shares have been delivered and applicable restrictions |
| Primary risk | Concentration in employer stock and plan-related risks | Share-price fluctuations and equity compensation conditions |
The details of each arrangement depend on the plan documents and applicable law. Employees should not assume that all ESOPs or RSU programs operate identically.
ESOP vs RSU: How Are They Taxed?
Tax treatment is one of the most important differences between ESOPs and RSUs.
ESOP Tax Treatment
ESOPs generally receive tax treatment associated with qualified retirement plans.
In many cases, employer contributions and investment growth within a traditional ESOP are not taxed to employees as current wages when allocated to their accounts. Taxes generally arise when participants receive taxable distributions, subject to the applicable rules.
The treatment of distributions depends on factors such as the type of distribution, the participant’s circumstances, and the applicable tax provisions. Eligible distributions may qualify for special treatment, while early distributions can trigger additional taxes unless an exception applies.
Participants should review the plan’s distribution rules and the IRS guidance on retirement plan distributions.
The IRS ESOP overview provides further information about the plan’s structure and requirements.
RSU Tax Treatment
RSUs generally create ordinary wage income when shares are transferred to the employee at settlement, assuming a typical stock-settled award.
For example, if 400 RSUs settle when the stock price is $75, the gross compensation value is generally $30,000.
Federal income tax withholding and applicable employment taxes may apply. The amount withheld is not necessarily equal to the employee’s final tax liability.
If the employee later sells the shares, the sale may create a capital gain or loss based on the relevant cost basis and sale price.
For further information, see IRS Publication 525: Taxable and Nontaxable Income.
Which Has Better Tax Treatment?
There is no universal answer. Traditional ESOPs and RSUs follow different tax frameworks, so a direct comparison requires considering when the benefit becomes taxable and when the employee can access the money.
An ESOP may provide tax-deferred retirement benefits under applicable rules. RSUs generally create taxable wage income when shares are transferred.
Employees should consider their own circumstances and consult a qualified tax professional before making decisions based on either arrangement.
Benefits of an ESOP
ESOPs can offer several advantages for eligible employees.
Retirement Savings
An ESOP can provide a source of retirement benefits through employer stock held in the plan.
This may supplement other retirement savings, such as a 401(k), depending on the employer’s benefit structure.
Employer-Funded Ownership
Employees generally receive allocations under the plan rather than purchasing the allocated shares directly with personal funds.
The value of those allocations depends on the plan’s terms and the company’s stock value.
Potential Long-Term Growth
If the employer performs well and its stock value increases, an employee’s ESOP account may grow.
However, stock values can also decline, and future performance is uncertain.
Employee Ownership Culture
ESOPs can give employees a financial interest in the business and may support a culture of shared ownership.
The financial effect depends on the company’s management, plan design, and overall performance.
Benefits of RSUs
RSUs can provide advantages for employees who receive equity as part of their compensation.
No Exercise Price
Unlike stock options, RSUs generally do not require employees to pay an exercise price to receive the shares after vesting.
Taxes may still be withheld, and the employee may receive fewer net shares.
Potential Compensation Growth
If a company’s stock price increases before the RSUs settle, the value of the award may increase.
For example, 300 RSUs settling at $80 per share have a gross value of $24,000.
Transparent Vesting Schedules
RSU award agreements typically specify the vesting conditions and dates.
Employees can use this information to understand when they may become entitled to receive shares.
Flexibility After Settlement
Once shares are delivered, employees may be able to hold or sell them, subject to trading restrictions, company policies, and applicable law.
Publicly traded shares may be easier to sell than private-company shares, although liquidity is not guaranteed in every circumstance.
Risks and Limitations of ESOPs and RSUs
Both arrangements have risks that employees should understand.
ESOP Risks
An ESOP may concentrate a significant portion of an employee’s retirement benefits in the employer’s stock.
If the company performs poorly, employees could experience a decline in their retirement account value at the same time that their employment income is at risk.
ESOP participants should also understand distribution restrictions, vesting requirements, and the plan’s valuation and diversification provisions.
RSU Risks
RSU values can decline if the share price falls. Unvested awards may be forfeited if employment ends before the applicable vesting conditions are satisfied.
Employees at private companies may also face restrictions on selling shares.
Additionally, RSUs can increase an employee’s financial exposure to the employer because both salary and equity compensation depend on the same company.
Employees should consider diversification and avoid treating projected equity values as guaranteed income.
ESOP vs RSU: Which Is Better for Employees?
The better option depends on the employee’s goals, compensation package, retirement needs, and financial circumstances.
An ESOP may be particularly relevant to employees who want an employer-sponsored retirement benefit and are comfortable with the plan’s investment and distribution structure.
RSUs may be attractive to employees who receive equity as part of annual compensation and want the opportunity to benefit from stock-price growth.
However, neither arrangement is automatically better for every employee.
When comparing an ESOP with an RSU offer, consider:
- The expected value of the benefit.
- The vesting schedule and eligibility requirements.
- The timing of access to the funds.
- Applicable tax treatment.
- The employer’s financial condition.
- The ability to diversify investments.
- The terms that apply when employment ends.
Employees should also compare the complete compensation package, including salary, bonuses, retirement contributions, health benefits, and other incentives.
A benefit with a larger projected value may not necessarily provide greater immediate financial flexibility.
Frequently Asked Questions
Is an ESOP the same as an RSU?
No. An ESOP is generally a qualified retirement plan that invests primarily in employer stock. An RSU is an equity compensation award that typically delivers shares or cash when specified conditions are satisfied.
Do employees pay taxes on ESOP shares?
Traditional ESOP benefits generally receive tax treatment under qualified retirement plan rules. Tax is often deferred until a taxable distribution, although the outcome depends on the distribution and applicable law.
Are RSUs taxed when they vest?
For typical stock-settled RSUs, ordinary wage income generally arises when shares are transferred to the employee at settlement. The precise timing can depend on the award structure and applicable tax rules.
Can employees sell ESOP shares immediately?
Not necessarily. ESOPs operate under retirement plan distribution provisions, and participants generally cannot treat their account balance as freely tradable stock. Access depends on plan terms and applicable law.
Can employees lose their RSUs?
Unvested RSUs may be forfeited if the employee does not meet the award’s conditions. Vested awards are governed by their settlement terms and other applicable restrictions.
Can a company offer both an ESOP and RSUs?
Companies may provide multiple types of employee benefits, but the availability and structure depend on the employer, plan design, and legal requirements. The two arrangements serve different purposes and follow different rules.
Conclusion
The difference between ESOP vs RSU comes down to the structure and purpose of each benefit.
An ESOP is generally a retirement plan that holds employer stock for participating employees. RSUs are compensation awards that typically deliver shares or cash after vesting and settlement conditions are met.
Both can provide financial benefits, but neither guarantees a particular return. ESOP values depend on employer stock performance and retirement plan rules, while RSU values depend on share prices, vesting conditions, and settlement terms.
Employees should review the governing documents, understand the tax implications, and consider how each benefit fits into their broader financial plans.
Disclaimer: This article is for educational purposes only and does not constitute tax, legal, retirement, or investment advice. ESOP and RSU rules vary according to plan documents and individual circumstances. Consult a qualified professional for guidance specific to your situation.